
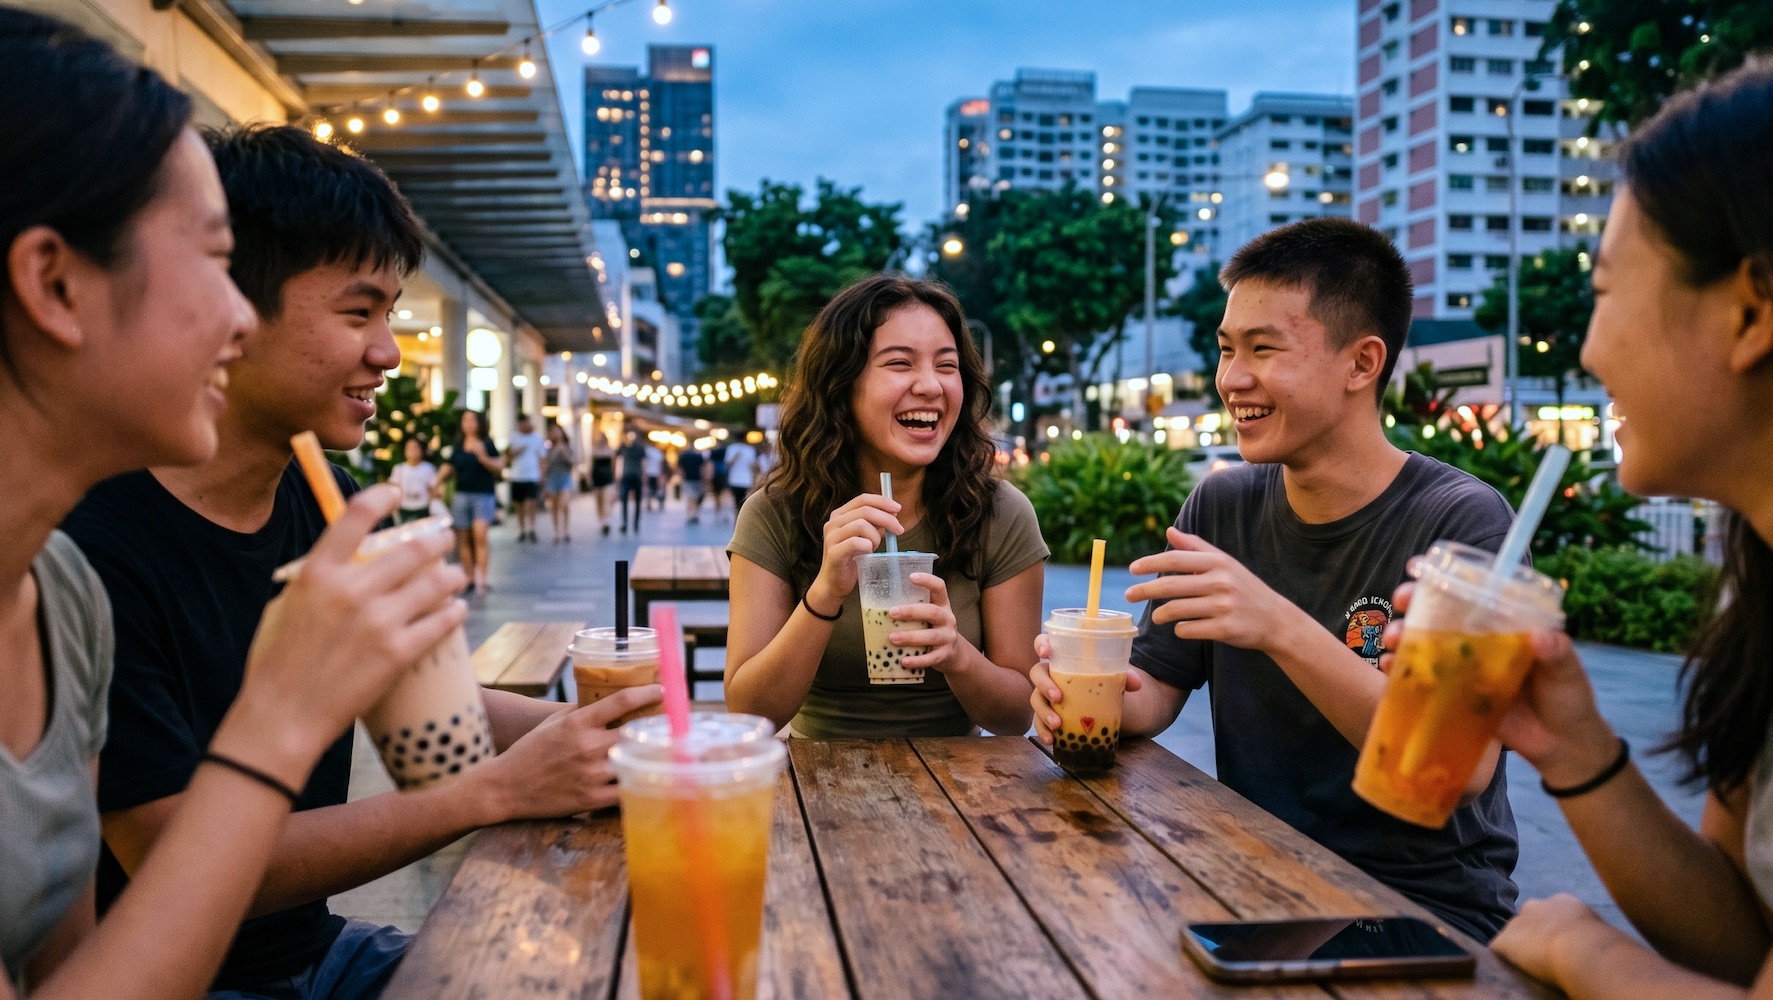
Just yesterday they were struggling with their PSLE, and now they are towering over us in their Secondary School uniform. It feels like just as they start getting taller, their "needs" start getting more expensive. In secondary school, money isn't just for the canteen anymore; it's for social bonding, transport, and data plans. The main perspective we need to adopt is The Training Wheels Phase. We want them to make small mistakes with $50 now, rather than big mistakes with $5,000 later. It's about shifting from a "pay-per-day" system to a monthly budget that rewards discipline and punishes impulsivity in a safe environment.
Quick Wins: Immediate Shifts for the Teen Budget
Moving to a monthly system forces teens to think ahead. These tactical shifts bridge the gap between "asking for money" and "managing money" without causing a household crisis.
1. Transition to a monthly allowance
Give them the full month's budget on the 1st. If they spend it all by the 10th, they must eat home-packed bread for the remaining 20 days. This "hard limit" is the most effective teacher of delayed gratification.
2. Set up a teen-friendly debit card
Use apps like Revolut <18 or POSB Smart Buddy. It allows them to tap for MRT and meals while giving you a real-time view of their spending patterns without hovering over their shoulder.
3. Create a "Social Buffer" category
Accept that "hanging out" is part of their development. Instead of judging every bubble tea, set a fixed "Social Fund." Once that's gone, they must decline outings. It teaches them to choose their events wisely.
4. Automate the "Transport Top-up"
Link their SimplyGo to your credit card but set a threshold alert. Explain that this is a utility, and any unnecessary Grab trips will be deducted from their "fun money" for the following month.
5. The "Brand Name" trade-off talk
When they ask for a $150 hoodie, offer the price of a standard $30 version. They must fund the $120 "brand premium" from their own savings. This immediately clarifies the difference between utility and status.

The Long Game: Building Life-Long Money Habits
Financial literacy is a marathon. These strategies focus on long-term wealth concepts, the responsibility of earning, and the reality of recurring costs to build life-long independence.
1. Introduce the "Subscription" audit
Teens love Spotify, Netflix, and gaming passes. Make them responsible for at least one digital subscription. Seeing $12 leave their account every month teaches them about the "hidden" cost of recurring digital lifestyles.
2. Open a "First Investment" account
Once they have a small nest egg, help them put a portion into a high-yield savings account or Robo-advisor. Seeing money grow by even a few cents introduces the concept of "passive income" early.
3. Discuss the "Cost of Earning"
Encourage a safe part-time job or internship during the long year-end holidays. There is no better way to understand the value of $10 than having to stand on your feet for an hour to earn it.
4. Set a "Big Purchase" goal
Whether it's a new phone or console, set a matching goal: "If you save $300, I will pay the remaining $300." This creates a long-term project that requires months of disciplined saving and research.
5. Financial transparency at home
As they mature, let them see the "boring" side of adulting. Show them the electricity bill or grocery receipt. Understanding the family's "run rate" makes them more empathetic and less likely to make unreasonable demands.
The "Ignore" List: Low ROI Habits for Teen Finance
-
Micro-managing small "frivolous" buysDon't nag about every $2 stationery item or $6 bubble tea. If they stay within their monthly budget, the "how" doesn't matter. Over-policing leads to them hiding their finances from you.
-
Banning social outings as a "cost-saving" measureSocialising is the primary "work" of a teenager. Cutting their budget to the point of social isolation breeds resentment. View the social fund as a developmental necessity, not a waste.
-
Complex accounting spreadsheetsUnless your teen is a math whiz, a 15-tab Excel sheet will bore them. Stick to simple apps or a basic "Income vs Expense" notebook. The goal is the habit of tracking.
-
Financial punishments for bad gradesDocking allowance for a bad Math score mixes two different issues. Money should be a lesson in management; grades should be a lesson in effort. Avoid mixing the two.
-
Comparing with "wealthy" classmatesEvery family's situation is different. Don't let "But my friend gets $500!" sway you. Stick to your family's values. Explain that their allowance is based on your family's plan.
The Savvy Parent's Teen Budget Master Checklist
-
1. Monthly allowance system initiatedWe have officially moved from a daily pocket money system to a fixed monthly bank transfer.
-
2. Tracking app or debit card activatedThe teen has a Revolut <18, POSB Smart Buddy, or similar card linked to their own tracking app.
-
3. Social "Hangout" fund agreed uponA clear limit for weekend outings and "fancy" meals has been set and understood.
-
4. SimplyGo transport link explainedThe teen understands that transport is a capped utility and excessive private hires come out of their fun money.
-
5. "Brand Premium" policy establishedWe have agreed that the family pays for "needs" (basic gear) while the teen pays for "labels."
-
6. Digital subscription audit completedThe teen has chosen one monthly subscription (Spotify/iCloud/Game Pass) to fund themselves.
-
7. Holiday "Work Experience" goal setA plan for a part-time job or internship during the long holidays has been discussed to teach earning power.
-
8. High-interest "Teen Savings" account openedThe teen has a dedicated account where they can see their festive money and savings grow.
-
9. Household bill transparency session heldWe have sat down to look at the real costs of the air-con, Wi-Fi, and groceries to build empathy.
-
10. "No Questions Asked" emergency fund readyA small, separate buffer exists for genuine emergencies (like a lost EZ-link) to ensure they are never stranded.